Between the 2003 and 2009 ice storms, recurring tornado tracks, and the April 2025 record flood, Franklin County homeowners have learned that weather is a leading cause of HVAC replacement. The question that follows every event: will insurance pay? The answer is 'usually yes — if the event was sudden and your documentation is good.' Here's how that works in practice.
We've documented storm damage for adjusters across every weather event this county has staged, and the claims that move smoothly share the same habits.
The Coverage Rule: Sudden vs. Gradual
Kentucky homeowner policies generally cover sudden, accidental damage: a tree limb crushing a condenser in an ice storm, lightning killing a control board during an outage, wind toppling a unit, hail shredding coils. What they typically exclude is gradual — the rusted-out unit that finally failed, the deferred maintenance that invited the failure, the slow leak nobody addressed.
River flooding is its own category: standard homeowner policies exclude flood damage unless you carry flood insurance (NFIP or private), which most mortgaged river-adjacent Frankfort homes are required to carry. Sewer and sump backups follow their own riders. Know which policy responds to which water before the water comes.
The Deductible and ACV-vs-RCV Reality
Your out-of-pocket usually starts at your deductible — and storm years can include separate wind/hail deductibles that differ from your standard one, worth reading before the season. The bigger variable is Actual Cash Value versus Replacement Cost Value: ACV pays the depreciated value of your old unit; RCV pays replacement cost, often with the depreciation held back until work completes.
RCV policies are the better protection and the more common modern form, but the holdback structure means claims involve paperwork after the install. We provide the completion documentation that releases those funds.
Need this handled by a pro today?Same-day service across Franklin County • 24/7 emergency dispatch
Call +1 (327) 210-5999Documentation: The Claim's Whole Game
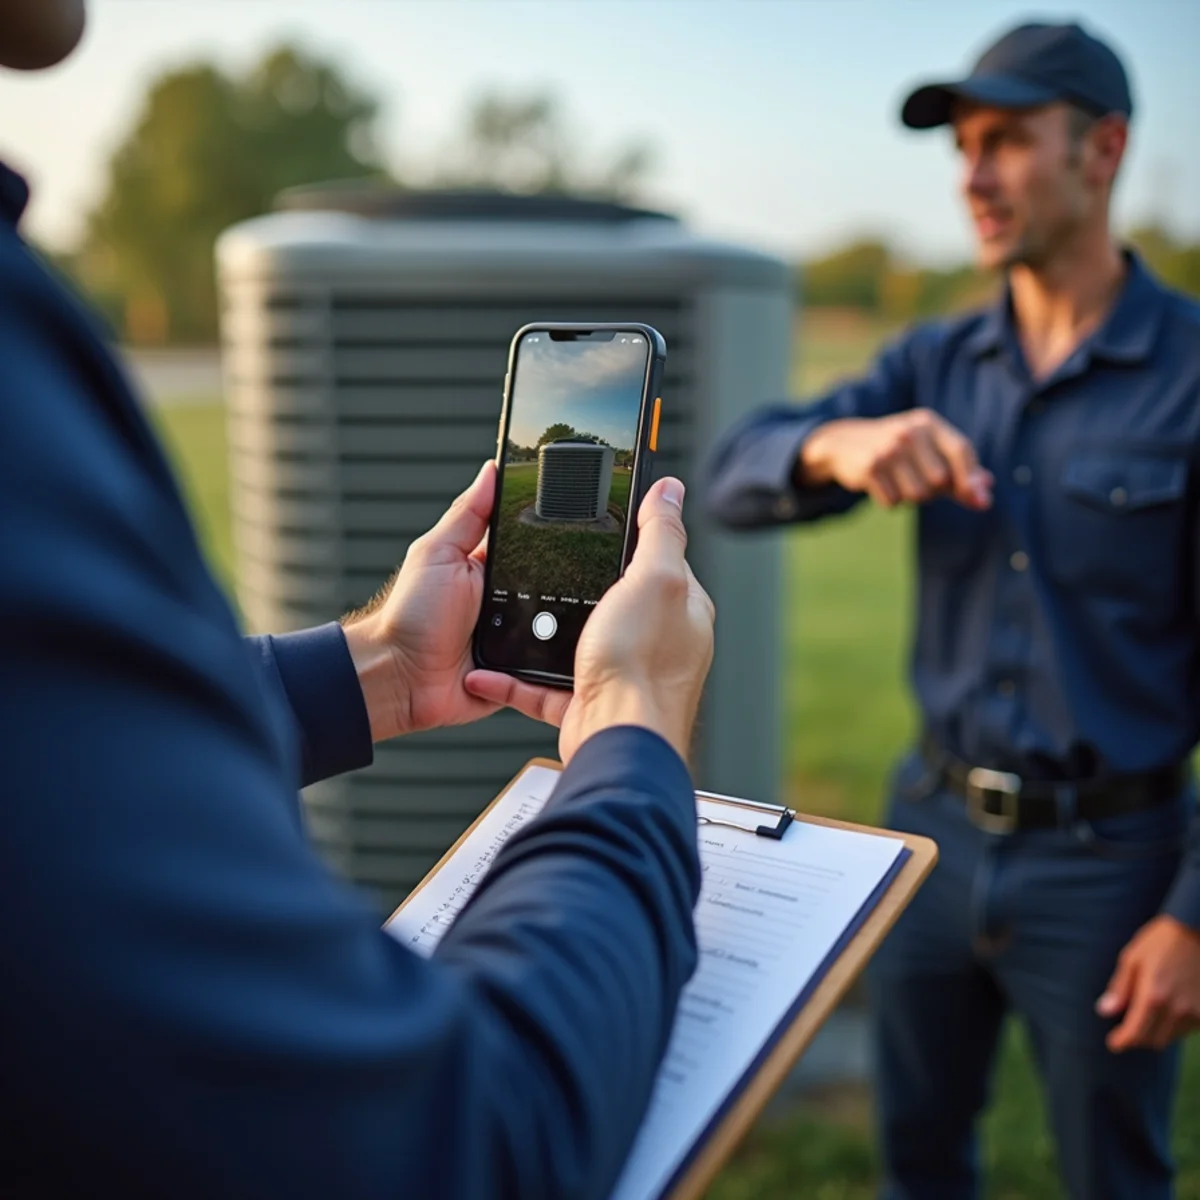
The claims that stall are the ones with thin evidence. The claims that move have: dated photos of the damage before anything was touched, model and serial plates, the failed components, and a professional itemized estimate in the format adjusters expect. That's exactly what our storm-response documentation includes — photos, readings, water lines where relevant, and line-coded estimates.
Two homeowner habits matter as much: don't start the system after storm or flood damage (running damaged equipment worsens the loss and muddies causation), and don't dispose of the damaged unit until the adjuster has seen it or your documentation is complete.
- Dated photos of the damage before anything is touched — water lines, ice, debris, model plates.
- The failed components photographed and retained until the adjuster has seen them.
- A professional itemized estimate in adjuster format — line-coded, with readings.
- Notes on cause and timing: sudden event versus deferred maintenance is the argument that decides coverage.
- Your policy's declarations page: wind/hail deductible, ACV vs. RCV, and flood coverage confirmed before the season.
When the Adjuster and the Contractor Meet
Most claims settle without drama when the estimate is clean. When adjusters ask questions — scope, necessity of elevation work, repair-vs-replace judgment — we answer them directly and in writing. We've been through this cycle enough times to know what a file needs, and we can speak with your adjuster on your behalf if the conversation stalls.
One upgrade worth discussing on any flood claim: elevating the replacement above the historical high-water mark. Carriers vary on covering elevation, but post-flood it's the smartest money in the project — the difference between the next event being a cleanup or another claim.
A Pre-Storm Checklist for Franklin County
Before storm season: photograph your equipment and plates (a dated 'healthy' photo speeds causation questions), read your declarations page for wind/hail and flood coverage, verify your maintenance is documented (it separates sudden from gradual), and know where your HVAC breakers are. After any event: photos first, no restarts, and an early professional assessment.
Kentucky weather writes the claims; documentation decides who pays. Call +1 (327) 210-5999 after any storm event and we'll handle the technical side of that equation.
The Bottom Line
Insurance claims reward documentation and punish improvisation: photograph before cleanup, don't restart damaged equipment, and get professional documentation in the format adjusters expect. We've built those files through every major event this county has staged — and we'll talk with your adjuster directly when questions come up.
Frequently Asked Questions
Yes — that's classic sudden accidental damage under standard policies, typically subject to your wind/hail or standard deductible. Documentation (photos before cleanup, the damaged unit, itemized estimate) is what makes it move quickly.
Most likely your policy excludes river flooding and no flood policy was in force — flood coverage is separate from homeowner insurance. Flood-damage claims run through NFIP or private flood carriers; the documentation requirements are similar.
Make the property safe and stop active damage (shut off systems, tarp where needed), but don't complete permanent repairs or discard damaged equipment before documentation. Emergency stabilization is usually covered; premature replacement can complicate the claim.